Renovation Contingency Budget: How Much to Set Aside
Set the right renovation contingency budget and avoid surprise bills. Call (833)-211-1668 for free quotes from local contractors.
By Olivia Owens
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
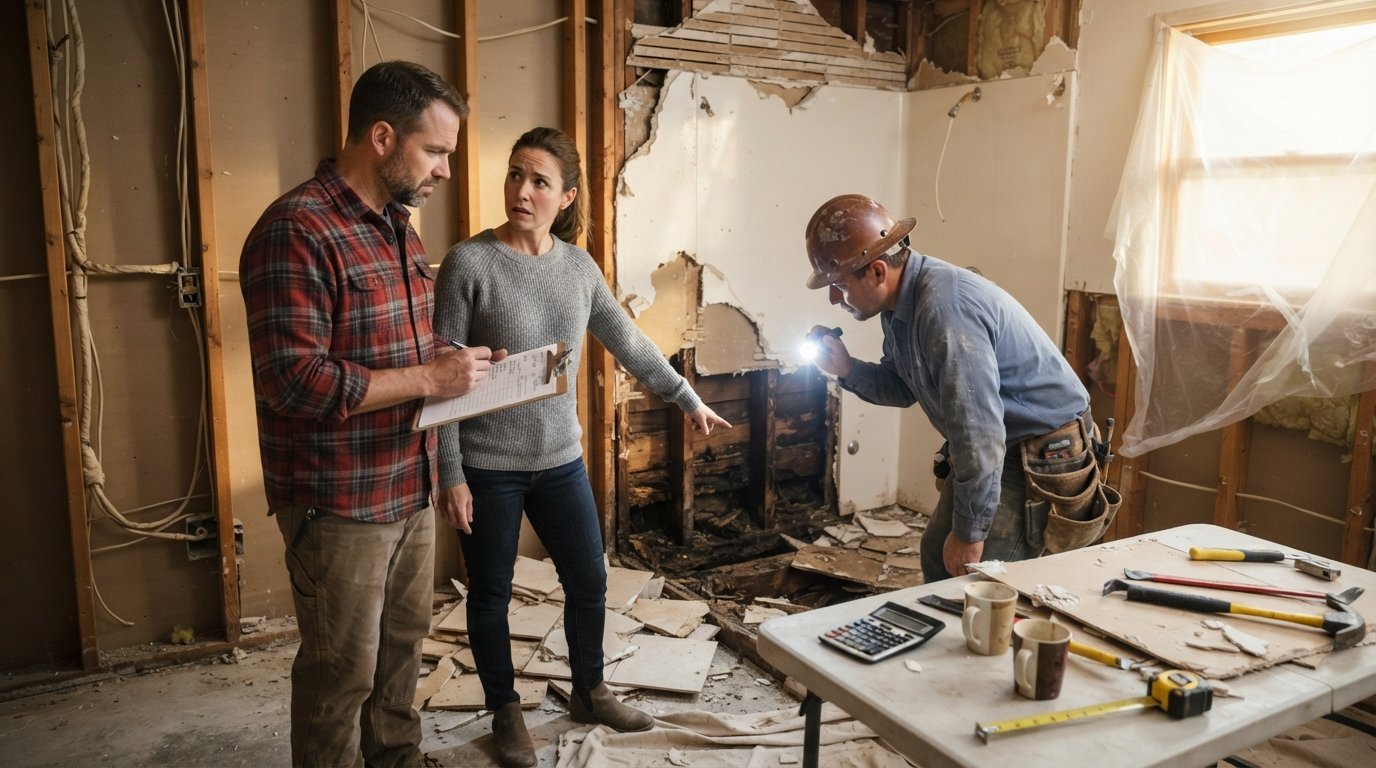
You have finalized the design, signed the contractor agreement, and written the first check. Then the crew opens a wall and finds decades-old wiring wrapped in cloth, or a joist that has been slowly rotting behind the shower tile. Suddenly, your carefully planned renovation has a new line item that nobody budgeted for. This exact scenario plays out on job sites across the country every single week, and it is the single most common reason remodeling projects stall, drag on, or end in financial stress. The good news is that this risk is almost entirely manageable. A properly sized renovation contingency budget is the difference between a project that bends under surprises and one that breaks.
The problem is that most homeowners either skip the contingency entirely or guess at a number that feels safe without any real basis. Setting aside too little leaves you exposed, while setting aside too much can make you abandon a project that was actually affordable. This guide walks through how much to reserve, what those funds are really for, where the money should sit while the work is happening, and when it is appropriate to spend it. By the end, you will know how to build a contingency line into your renovation budget with confidence and precision.
What a Renovation Contingency Budget Actually Covers
A renovation contingency budget is a block of money reserved specifically for costs that are unknown at the time the project is planned. It is not a slush fund for upgrades, and it is not a place to hide overages from poor planning. It exists because construction is inherently uncertain, especially in older homes where drawings and inspections cannot reveal everything hidden behind drywall, under flooring, or inside walls. A contingency is your financial shock absorber, and it should be treated as a legitimate, protected line item in the budget, not as leftover money that can be spent on nicer fixtures if nothing goes wrong.
It helps to separate two types of contingency: the design contingency and the construction contingency. The design contingency covers changes that occur during planning and permitting, such as a structural engineer requiring a larger beam than originally drawn. The construction contingency covers surprises discovered during the build itself, like discovering asbestos tile under a layer of vinyl or a plumbing vent that was never properly connected. For most homeowner renovations, the construction contingency is the larger and more important of the two, and it is the one most people underestimate.
Perhaps the most important mental shift is this: the contingency is not part of the project budget, it is insurance on top of the project budget. If your renovation is estimated at $60,000 and your contingency is $9,000, your true spending ceiling is $69,000. If you mentally fold the contingency into the project cost and spend it on finishes, you have effectively removed your safety net before the first nail is pulled.
Renovation Contingency Budget: How Much to Set Aside by Project Type
The right percentage depends heavily on what you are renovating, how old the home is, and how much of the work involves opening up walls or altering structure. A cosmetic refresh in a newer home carries far less risk than a full gut renovation of a century-old property. The table below reflects ranges that experienced contractors and cost estimators commonly use, but treat them as starting points and adjust upward for older homes, unknown prior work, or any project where you cannot see what is behind the surfaces.
- Cosmetic refresh (paint, flooring, fixtures, no walls opened): 5 to 10 percent of project cost. Risk is low because existing systems stay untouched.
- Mid-range kitchen or bathroom remodel (some walls opened, systems updated): 10 to 15 percent. Plumbing and electrical surprises are common once tile and cabinets come out.
- Full gut renovation of a single room: 15 to 20 percent. Everything is exposed, so everything can surprise you.
- Whole-home renovation or addition: 15 to 25 percent. Multiple trades, structural work, and permitting complexity multiply the unknowns.
- Historic or very old home (pre-1950): 20 to 30 percent. Outdated wiring, lead paint, asbestos, and non-standard framing are almost guaranteed.
These ranges exist because the probability of a hidden problem rises sharply the moment a wall is opened. In a cosmetic refresh, the worst case is usually a small patch or an unexpected outlet relocation. In a gut renovation, the worst case could be a failed inspection that requires rewiring an entire floor or replacing a section of rotted subfloor. The percentage is not arbitrary, it reflects the scope of exposure.
It is also wise to scale your contingency based on your own tolerance for risk and the accuracy of your contractor estimates. If your contractor provides a detailed, line-item estimate with allowances clearly marked, you can lean toward the lower end of the range. If you are working from a rough ballpark or a handshake number, lean higher. And if you are managing the project yourself as an owner-builder, add another 5 percent, because you are absorbing coordination risk that a general contractor would normally carry.
Hidden Issues That Blow Through Contingency Funds
Understanding what tends to go wrong helps you decide how much to reserve and where to focus your pre-construction inspection. The most expensive surprises are rarely cosmetic. They are structural, mechanical, or health-related, and they usually require immediate attention because work cannot legally or safely continue until they are resolved.
Outdated wiring is one of the most common and costly discoveries. Homes built before the 1970s often contain aluminum wiring, knob-and-tube wiring, or circuits that are not grounded. Once walls are open, an inspector may require that the exposed wiring be brought up to current code, which can add thousands of dollars in a single afternoon. Similarly, galvanized steel plumbing or polybutylene supply lines may be corroded or failing, and replacing them while walls are open is far cheaper than doing it later, but it is still an unbudgeted expense.
Rot and water damage hide behind tile, under sinks, and inside exterior walls. A slow leak can quietly destroy subfloor, framing, and even structural headers over years without any visible sign. When the demolition crew pulls out a vanity or a shower pan, they may find that the entire wall cavity needs to be rebuilt. Foundation surprises are rarer but far more expensive. A cracked footing, an undersized beam, or soil movement can require engineering and structural repair that easily consumes an entire contingency and then some.
Environmental hazards add another layer. Asbestos in floor tile, pipe insulation, or popcorn ceilings, and lead paint in homes built before 1978, both require certified abatement before work can proceed. These are not optional fixes, they are legal requirements, and they can add several thousand dollars to a project with almost no warning.
If your contractor exceeds the agreed budget because of these kinds of discoveries, the situation can become tense. Our guide on what happens if a contractor exceeds budget explains your options and how to protect yourself when costs climb beyond the original estimate.
How to Hold Contingency Funds So They Stay Available but Unspent
Where you keep your contingency money matters almost as much as how much you set aside. The goal is to make the funds instantly available when a surprise appears, but difficult enough to access that you do not casually spend them on upgrades or impulse decisions. The worst place for contingency money is a general checking account that also pays for daily life, because it will quietly disappear into groceries, bills, and weekend spending.
A better approach is to open a separate, dedicated savings account specifically for the renovation. Label it clearly, fund it fully before construction begins, and do not link it to your primary debit card. This creates a small but meaningful friction barrier. If you prefer even more discipline, consider a short-term certificate of deposit that matures around your project midpoint, though be aware that early withdrawal penalties could reduce your available funds if a surprise hits early.
It also helps to set a personal rule: no contingency withdrawal without a written change order or a documented, photographed problem. Every time you pull money from the contingency, record the date, the amount, the reason, and the remaining balance. This running log keeps you honest and gives you a clear picture of how much cushion remains as the project progresses. If you are halfway through the build and have spent 80 percent of your contingency, that is a signal to slow down and reassess scope before committing to the next phase.
Finally, communicate the contingency plan to your contractor. Let them know that you have reserved funds for surprises and that you expect a written change order with a cost breakdown before any additional work begins. A professional contractor will respect this, and it sets a tone of financial discipline from day one.
When a Change Order Should Draw From Contingency vs. Renegotiate Scope
Not every unexpected cost should automatically come out of your contingency. Some changes are genuinely unforeseen and unavoidable, while others are really scope changes that you or the contractor introduced. Knowing the difference protects your budget and keeps your project on track.
Draw from contingency when the cost is caused by a condition that could not reasonably have been discovered before demolition, such as hidden rot, code violations in existing work, or a structural defect. These are the risks the contingency exists for. Also draw from contingency when a required inspection or permit triggers a mandatory fix that was not in the original scope, such as adding a GFCI outlet to bring a kitchen up to code.
Renegotiate scope instead when the change is optional, aesthetic, or driven by a decision you made after the project started. If you decide mid-renovation that you want a farmhouse sink instead of the standard model, or you want to add a pantry cabinet that was not in the plan, that is a scope change, not a contingency event. Pay for it by removing something else from the project or by increasing your overall budget, not by draining the safety net.
If the contractor claims a charge is a contingency item but you suspect it was caused by their own error or omission, ask for documentation. Photos, inspection reports, and a written explanation should accompany any request to use contingency funds. If the explanation does not hold up, that is a negotiation conversation, and you may need to push back firmly. In extreme cases, a contractor who repeatedly overruns the budget without justification may need to be replaced, which is a decision no homeowner wants to make but sometimes must.
Building Contingency Into Your Quote Comparison Process
One of the best ways to protect your renovation budget is to compare contractor quotes carefully before you hire anyone. A detailed, line-item estimate tells you how much of the cost is fixed and how much is an allowance that could shift. When you compare bids side by side, you can spot which contractors have padded their numbers with vague allowances and which ones have done the homework to price the job accurately.
As you review quotes, ask each contractor directly how they handle unexpected discoveries. Do they stop work and issue a change order, or do they proceed and bill later? Do they include a contingency line in their own pricing, or do they expect you to carry it? Their answers will tell you a lot about how the project will go once the walls come down.
If you are still in the early stages of finding the right professional, a service like Contractor.Homes can connect you with pre-vetted local contractors and free quotes, which makes it easier to gather multiple detailed estimates and compare them on equal footing. Getting three or four quotes before you commit is one of the simplest and most effective ways to make sure your contingency percentage is based on reality rather than guesswork.
Once you have your quotes, build your total project budget, then add the contingency on top. Do not subtract the contingency from the lowest bid to make the project fit your savings. Instead, use the contingency range as a filter: if the lowest bid plus a reasonable contingency still fits your finances, the project is viable. If it does not, you either need to reduce scope or wait until you have more cash available.
Final Thoughts on Protecting Your Renovation Budget
Setting aside the right renovation contingency budget is not about expecting the worst, it is about planning for reality. Construction always includes unknowns, and the homeowners who handle them best are the ones who reserved money before the first hammer swung. Aim for 10 to 15 percent on typical remodels, 15 to 25 percent on gut renovations and additions, and higher on older homes. Keep those funds in a separate account, track every withdrawal, and distinguish between genuine surprises and optional upgrades. Do that, and a hidden problem behind the wall becomes a manageable line item instead of a project-ending crisis.