Contractor Abandoned the Job? Steps to Protect Your Home
Facing a walkout? Learn what to do if a contractor abandons the job mid project, from securing the site to recovering deposits. Call (833)-211-1668 for vetted pro connections.
By Sophie Reed
Learn more about General Contracting for guides, costs, and what to expect.
Compare General Contracting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
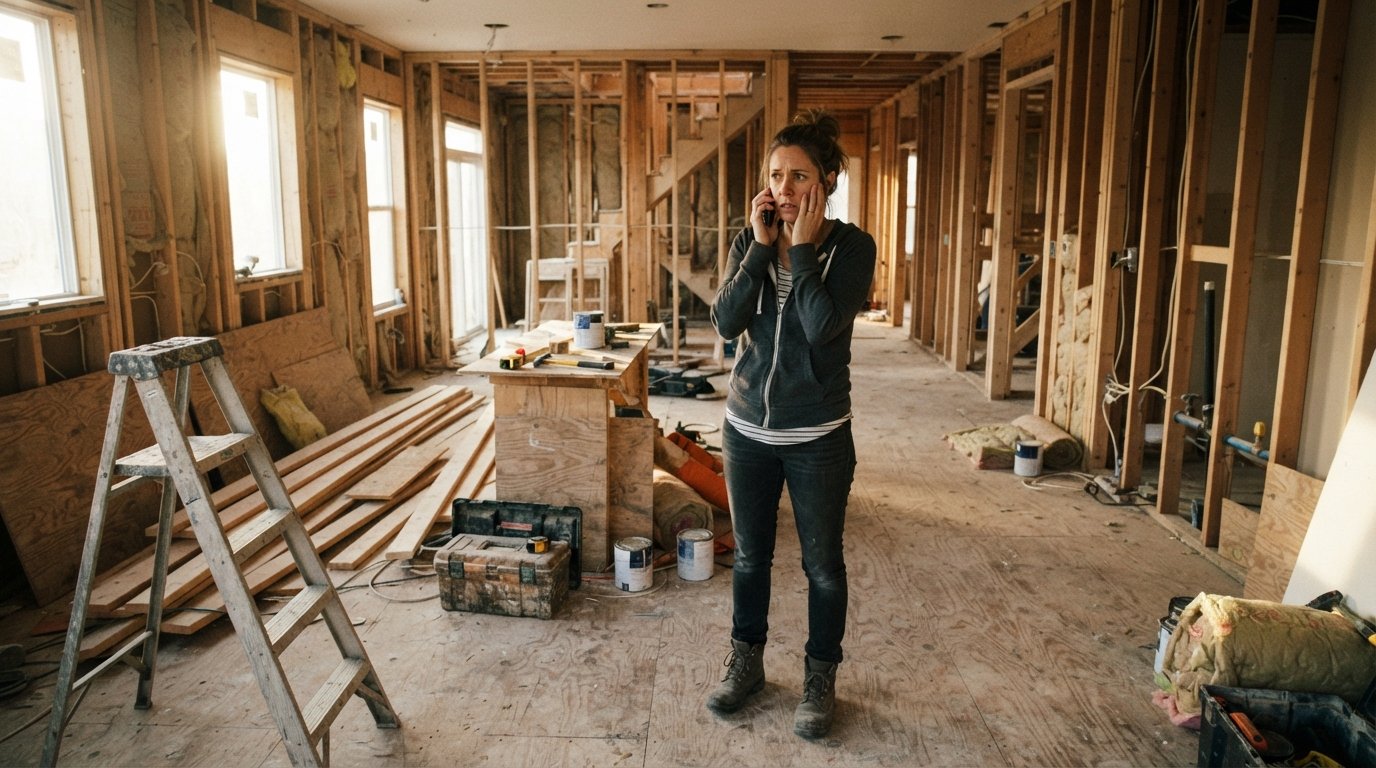
Your contractor's truck has not been seen in four days. The crew's tools are gone, the subfloor is still open, and your calls go straight to voicemail. The realization hits: you may be dealing with an abandoned job. This situation is more common than most homeowners expect, and it usually happens at the worst possible moment, after a deposit has been paid and the project sits half-finished. The good news is that you have more leverage than you think, provided you act quickly and methodically. This guide walks you through exactly what to do if a contractor abandons the job mid project, from securing your property and documenting the walkout to recovering your money and hiring a reliable replacement without paying twice for the same work.
Secure the Site and Document the Abandonment
The first 48 hours after you suspect abandonment are critical for two reasons: safety and evidence. An unfinished construction site is a hazard, and the condition of that site becomes the foundation of any legal claim, insurance dispute, or licensing complaint you file later. Before you touch anything, take a breath and think of yourself as an investigator building a case. Your documentation will do the talking if this ends up in small claims court or a state licensing board review.
Start by walking the property and photographing everything. Capture wide shots of each room or area under construction, then close-ups of specific defects, missing materials, exposed wiring, and unprotected openings. Take a timestamped video walkthrough narrating what you see. If the contractor left materials on site, photograph those too, since ownership of those materials may become a point of dispute. Do not discard or sell any materials yet; they may be evidence or leverage.
Next, secure the site physically. Board up open windows or doors, lock gates, and turn off utilities that could be dangerous if left unattended. If there is exposed electrical work, call a licensed electrician to make it safe. Document that emergency call and its cost, because it may be recoverable. If the project involves a roof or structural opening, a tarp or temporary patch is worth the expense to prevent water damage that your insurance might otherwise exclude.
Then, put the contractor on written notice. Send a certified letter and an email (so you have two paper trails) stating the date you last saw work activity, the work that remains incomplete, and a deadline for the contractor to respond, typically 10 business days. Keep the tone factual, not emotional. This letter matters because many contracts and state laws require written notice and a chance to cure before you can terminate the agreement or file a claim. Track every attempt to contact the contractor, including calls, texts, and emails, with dates and times.
Review Your Contract, Payment Schedule, and Lien Exposure
Once the site is safe and documented, pull out your contract and read it with fresh eyes. The payment schedule is your first line of defense. Most reputable contracts tie payments to completed milestones, not to arbitrary dates. If you have been paying ahead of progress, you are in a weaker position, but you are not without options. Calculate exactly how much you have paid and compare it to the value of the work actually completed. This gap is the number you will be fighting over, so know it precisely.
Lien exposure is the hidden risk in any abandonment. In many states, subcontractors and material suppliers who were not paid by the general contractor can file a mechanics lien against your property, even though you already paid the general contractor. This is why lien waivers matter. A lien waiver is a document in which a contractor or supplier confirms they have been paid and gives up their right to file a lien. If you collected conditional or unconditional lien waivers as payments were made, you are in a much stronger position. If you did not, contact the subcontractors and suppliers directly to find out whether they have been paid. Ask each one for a lien waiver or a statement of account. If they have not been paid, you may need to pay them directly to protect your title, and then pursue the general contractor for reimbursement.
Also check the contract for termination clauses, arbitration clauses, and notice requirements. Some contracts specify that disputes go to mediation or arbitration rather than court, which changes your strategy. Look for a clause that addresses abandonment or default, since many contracts define what happens if the contractor stops work for a certain number of days. If your contract requires written notice and an opportunity to cure, send that notice exactly as specified. Following the contract's own rules strengthens your position if you later need to sue or defend against a claim.
Recover Your Deposit Through Bonds, Insurance, or Small Claims
Recovering money after an abandonment depends on what protections were in place before the project began. The most common paths are a surety bond, a contractor's insurance policy, and small claims court. Each has different requirements and limits, so evaluate them in parallel rather than one at a time.
If your state or local jurisdiction requires contractors to carry a surety bond, you may be able to file a claim against that bond. Surety bonds are designed to compensate homeowners for certain losses caused by a licensed contractor's failure to perform, including abandonment. The claim process usually starts with the bonding company, and you will need your contract, payment records, photos, and the written notice you sent. Bond claim amounts are often capped, sometimes at the amount of the bond, so check the specifics for your state. Licensing boards can also discipline the contractor, which sometimes motivates a settlement.
Small claims court is often the most accessible route for deposits under your state's limit, which typically ranges from $2,500 to $25,000 depending on where you live. You do not need a lawyer for small claims, and filing fees are modest. Bring your contract, payment proof, photos, correspondence, and a clear calculation of your losses. If the contractor is licensed, also file a complaint with the state licensing board; this creates a record and can lead to restitution funds in some states. For larger losses, consult an attorney about breach of contract claims, and ask whether your state's consumer protection statutes allow recovery of attorney fees.
Homeowner's insurance rarely covers contractor abandonment itself, since it is considered a contractual dispute rather than a peril like fire or theft. However, if the abandonment led to secondary damage, such as water intrusion through an unfinished roof, that damage may be covered. Review your policy and document the chain of events carefully. When you are ready to find a replacement, using a platform like Contractor.Homes can help you connect with pre-vetted local professionals and request competitive quotes, which also gives you documented market pricing to support your claim.
Hire a Replacement Contractor Without Paying Twice
Hiring a replacement is where many homeowners accidentally double their losses. The temptation is to hire the first available crew to get the project moving again, but that can lead to paying twice for the same scope, duplicating permits, or inheriting liability for the first contractor's defective work. Approach the replacement hire with the same discipline you would use for a new project, and put everything in writing.
Before you hire anyone, get a written scope of work that clearly separates completed work from remaining work. Have the replacement contractor inspect the site and document existing conditions, including any defects left by the first contractor. This protects you if the new contractor later claims the prior work caused problems. Ask for a fixed-price bid for the remaining scope, or a time-and-materials arrangement with a not-to-exceed cap. Require a new contract that references the original plans and permits, and confirm who will pull permits and close out inspections.
Payment structure matters just as much the second time. Use a milestone-based schedule with a modest deposit, and collect lien waivers at each payment. Retain a final payment until the project passes inspection and you receive a certificate of occupancy or final sign-off where required. Before signing, verify the new contractor's license, insurance, and bonding, and check references for similar projects. A shortlist of vetting steps can save you from repeating the same mistake:
- Verify the license number with your state licensing board and confirm it is active and in good standing.
- Request a certificate of insurance for general liability and workers compensation, and call the insurer to confirm coverage.
- Ask for three recent references from projects of similar size and scope, and actually call them.
- Confirm the contractor will pull permits in their own name and schedule inspections.
- Get the payment schedule and lien waiver process in writing before work begins.
Finally, notify your original contractor in writing that you are terminating the agreement for cause and that you will pursue recovery of any overpayment and additional costs. Keep the termination letter factual and reference the contract's termination clause. If you used a platform to find the original contractor, report the abandonment there as well, since vetting networks often have dispute processes and may remove bad actors. Documenting the replacement costs, including any premium you paid for emergency scheduling, strengthens your claim for damages.
Protect Yourself on the Next Project
The best defense against abandonment is a contract and payment structure that limit your exposure from day one. Before you hire any contractor, insist on a written agreement that includes a milestone-based payment schedule, a defined scope, a start and completion date, and a clear termination procedure. Never pay more than a modest deposit upfront, and never pay for work that has not been completed and inspected. Collect lien waivers as you go, and keep a project file with photos, receipts, and correspondence. If a contractor resists these terms, that resistance is itself useful information.
It also helps to understand the warning signs before they become a walkout. Repeated delays, requests for early payments, disappearing for days at a time, and vague answers about subcontractors or permits are all red flags. If you notice them, address them in writing early rather than waiting for the project to stall. A short, professional email asking for a status update and a revised schedule often surfaces problems while they are still fixable.
If abandonment does happen, remember that speed and documentation are your allies. Secure the site, send written notice, review your contract and lien exposure, pursue recovery through the bond or small claims court, and hire a replacement with a tightly written scope and payment plan. You can also reach out to (833)-211-1668 for guidance on connecting with vetted contractors and moving your project forward. With a methodical approach, you can protect your home, your money, and your peace of mind, and turn a stalled project into a completed one.