Are Home Warranties Worth It for Older Homes? A 2026 Guide
Are home warranties worth it for older homes? Weigh premiums, exclusions, and repair savings before you buy. Call (833)-211-1668 for contractor quotes.
By Adnan Nazir
Find Local Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
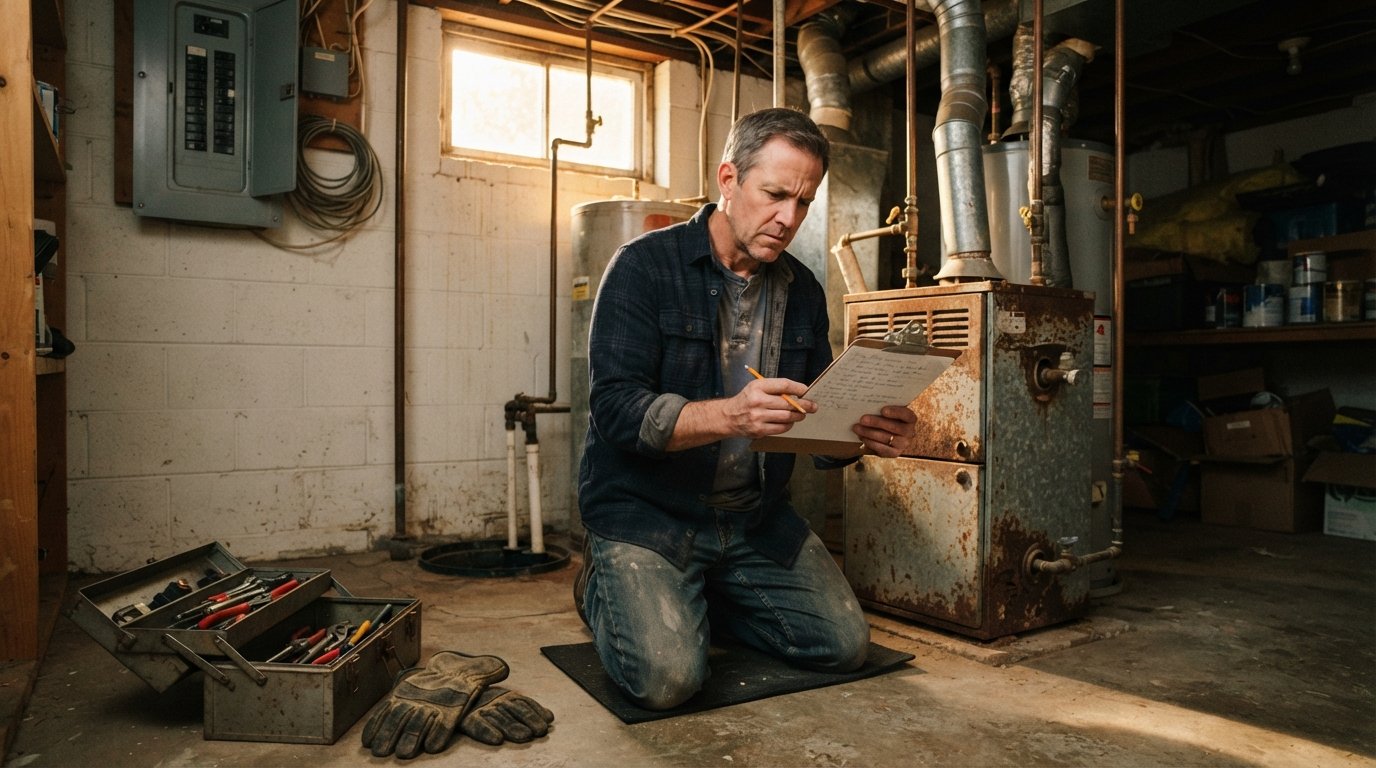
Your 1970s ranch has charm, but its original furnace is on borrowed time. The water heater rumbles like a freight train. And the electrical panel predates the personal computer. When you own an older home, every season brings a fresh repair bill, and the mailbox fills with glossy brochures promising that a home warranty will cover it all for a low monthly fee. Are home warranties worth it for older homes, or are they a financial trap dressed up as peace of mind? The answer depends less on the age of your house and more on the age of your systems, your tolerance for risk, and how carefully you read the fine print. This guide breaks down what these plans actually cover, what they quietly exclude, how claims interact with your choice of contractor, and when saving for repairs beats paying premiums.
What Home Warranties Typically Cover and Exclude
A home warranty is a service contract, not insurance. You pay a monthly or annual premium plus a per-claim service fee, and in exchange the provider dispatches a technician from its network to diagnose and repair covered items. The distinction matters for older homes because the systems that fail most often are exactly where the coverage gaps tend to hide.
On paper, a standard plan covers major mechanicals: heating and cooling systems, plumbing lines, electrical wiring, the water heater, and sometimes kitchen appliances. Some providers offer optional add-ons for pools, spas, well pumps, and septic systems. For a homeowner facing a $6,000 furnace replacement, the appeal is obvious. But the contract language that defines covered and excluded items is where the real cost lives, and older homes expose every ambiguity.
Common exclusions you will find in nearly every contract include:
- Pre-existing conditions and problems that existed before the policy started, which is a serious concern if your systems are decades old
- Items that were improperly installed or maintained, a clause providers frequently invoke to deny claims
- Code violations and permits, meaning the warranty may pay to fix a part but not to bring the repair up to current building code
- Disposal fees, haul-away costs, and permit costs, which can add hundreds to a major repair
- Cosmetic damage, such as rust, corrosion, or damage from a leak that was not fixed promptly
That last point deserves emphasis. In an older home, a slow leak under a slab or a corroded pipe joint often produces damage that the provider classifies as a maintenance failure rather than a covered breakdown. Before you sign, request the full sample contract, not the brochure, and read the exclusions section line by line. The list of what is not covered is usually longer than the list of what is.
Cost Versus Expected Payouts on Older Systems
The math of a home warranty comes down to a simple comparison: total annual premium plus service fees versus the expected cost of repairs. For a newer home, that math often favors the provider, because modern systems rarely fail. For an older home, the equation shifts, but not always in the homeowner's favor.
Suppose a plan costs $650 per year and charges a $100 service fee per claim. Over five years you pay about $3,250 in premiums. If your 25-year-old air conditioner fails and the warranty pays $4,000 toward replacement, you come out ahead. If your systems limp along and you file one or two small claims, you likely lose money. The average homeowner files roughly one claim per year, and many claims are for modest repairs that cost less than the combined premium and service fee.
Older homes also face a hidden cost: providers increasingly use depreciation schedules and coverage caps. A warranty might pay a fixed dollar amount for a water heater replacement based on its age, which can leave you covering the difference on a modern, higher-efficiency unit. Some contracts cap total payouts per item or per year, and a single major failure can exhaust the cap. The result is a plan that looks comprehensive on the sales page but covers a fraction of the real cost.
There is also the selection effect to consider. If your roof is 30 years old, most warranties will not cover it at all, and if your HVAC system is on its last legs, the provider may deny a claim by attributing the failure to wear and tear. In practice, the homes that need coverage most are the ones that face the most exclusions. That does not make warranties worthless, but it means the decision should be based on a realistic estimate of what the plan will actually pay, not the sticker price of a worst-case repair.
How Warranty Claims Interact with Contractor Choice
One of the least discussed downsides of a home warranty is the loss of control over who does the work. When you file a claim, the provider assigns a technician from its network. You generally cannot hire your own licensed plumber or HVAC contractor and expect reimbursement. In an older home, that restriction can create real problems.
Older properties often have quirks that a general technician may not anticipate: knob-and-tube wiring, undersized electrical panels, nonstandard plumbing layouts, or discontinued parts. A contractor who knows your neighborhood and your home's construction style is an asset. The warranty network, by contrast, may send whoever is next in the queue, and the quality of that work varies widely. Some providers pay network contractors low rates, which can lead to rushed diagnoses and repeated visits.
If you decide to pursue a warranty, ask two questions before signing: can you request a specific contractor, and what happens if the assigned contractor is unavailable or unqualified. Some plans allow a cash-out option where you accept a payout and hire your own professional, but the payout is typically far below market rate. For homeowners who value the ability to compare bids and choose a vetted local pro, the warranty model can feel like a step backward. If you prefer to keep control, our guide on contractor review incentives and what homeowners should know explains how to evaluate the professionals you hire directly.
There is a middle path. Use the warranty for small, predictable claims where the network is adequate, and handle major system replacements outside the plan so you can choose your own contractor. That hybrid approach captures some of the convenience while preserving your ability to get competitive quotes on the expensive work.
When Saving Toward Repairs Beats Paying Premiums
For many owners of older homes, the most reliable warranty is a dedicated savings account. Instead of paying $600 to $900 per year in premiums, set that amount aside each month into a home repair fund. After five years you have $3,000 to $4,500, which covers a water heater, a modest plumbing repair, or a significant portion of an HVAC replacement. The money is yours, earns interest, and carries no exclusions.
The savings approach works best when you can answer three questions honestly. First, what is the remaining life expectancy of your major systems? A home inspection or a quick assessment from a licensed contractor can give you a realistic timeline. Second, what is your cash reserve today? If a $5,000 failure would go on a credit card, a warranty may provide real value even with its limitations. Third, how much does uncertainty cost you in stress? Some homeowners sleep better with a plan in place, and that peace of mind has value.
A practical framework for deciding looks like this:
- List every major system and its approximate age, from the roof to the water heater.
- Estimate replacement costs for the three most likely failures in the next five years.
- Compare that total to five years of premiums plus expected service fees.
- Read the sample contract and cross out any system that is already near the end of its life, since it is likely excluded or capped.
- Decide whether the remaining covered items justify the premium, or whether a savings fund is the better bet.
Run this exercise every couple of years. As systems are replaced, the value of a warranty changes, and a plan that made sense for a 40-year-old furnace may be unnecessary once a new one is installed.
Practical Steps Before You Buy a Plan for an Older Home
If you are leaning toward a warranty, slow down and treat the purchase like any other contract. Start by requesting the full sample agreement and reading the sections on exclusions, coverage caps, pre-existing conditions, and cancellation. Check the provider's complaint history with your state insurance department or consumer protection agency. Confirm whether the plan requires a home inspection before coverage begins, and whether the provider can deny claims based on conditions found during that inspection.
Ask about the claims process in detail. How long does it take to dispatch a contractor? Can you get a second opinion if the diagnosis seems wrong? What happens if the assigned contractor cannot source parts for an older system? Some providers offer a buyout option when a covered item cannot be repaired, but the buyout amount is often based on depreciated value rather than replacement cost.
Also compare the warranty against the alternative: building a relationship with a reliable local contractor. A trusted professional who knows your home can spot problems early, recommend repairs before they become emergencies, and give you straight pricing. That relationship is difficult to replicate through a call center. If you are ready to compare quotes from vetted local pros, you can connect with pre-screened contractors through Contractor.Homes and request free estimates for the specific systems in your home.
Finally, remember that no warranty replaces basic maintenance. Older homes reward owners who stay ahead of small problems: flushing the water heater, changing filters, sealing leaks, and updating aging wiring. A warranty may cover a failure, but it will not prevent one, and providers are quick to deny claims when maintenance records are missing.
The Bottom Line on Older Homes and Home Warranties
Are home warranties worth it for older homes? Sometimes, but less often than the marketing suggests. They can make sense for a homeowner with limited cash reserves who faces a high probability of near-term system failures and who values the convenience of a single phone number. They make less sense for homeowners with savings, strong local contractor relationships, or systems already near replacement age, where exclusions and caps erode the value.
The smartest approach is to treat a warranty as one tool among several. Read the contract, run the five-year math, and keep a repair fund regardless of what you decide. Older homes demand attention, but with realistic planning and access to trustworthy local professionals, you can protect your budget without paying for coverage you may never use.
Find Local Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.