Home Improvement Loan vs Credit Card for Small Repairs
Compare home improvement loan vs credit card for small repairs and see which saves you more on interest. Call (833)-211-1668 for expert guidance.
By Olivia Owens
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
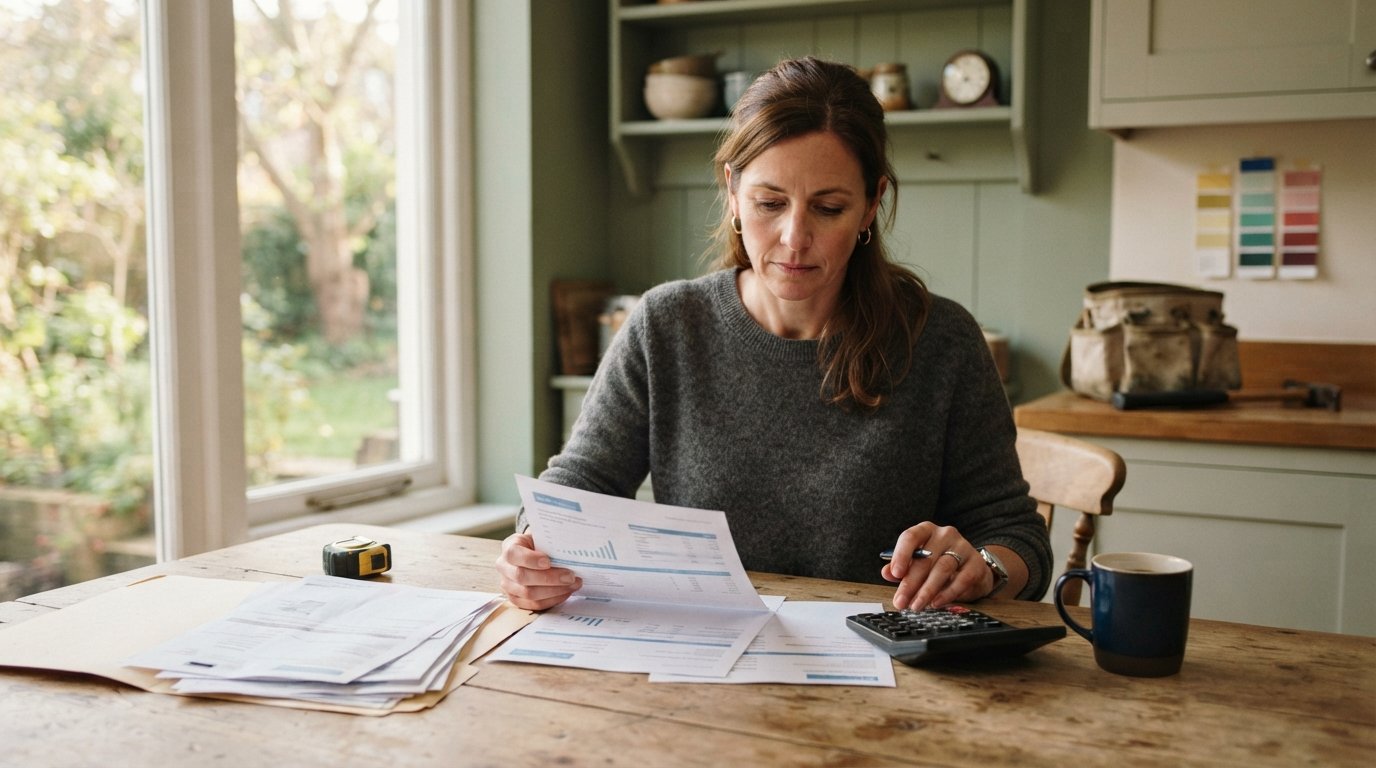
When a small repair turns into a mid-sized expense, the question is not whether to fix it but how to pay for it. A $6,000 roof patch, a $9,000 HVAC replacement, or a $12,000 bathroom subfloor repair can strain a household budget without warning. You have two common borrowing paths: a home improvement loan or a credit card. The right choice depends on the numbers, the timeline, and the fine print. This guide breaks down the real cost of each option so you can decide with confidence and avoid the traps that turn a manageable repair into a long-term financial headache.
How Home Improvement Loans and Credit Cards Differ
A home improvement loan is typically an unsecured personal loan or a secured home equity product designed for renovation and repair projects. You borrow a lump sum, repay it in fixed monthly installments over a set term, and pay interest on the declining balance. Credit cards, by contrast, are revolving lines of credit. You can charge the repair, carry a balance, and repay it at your own pace, but the interest rate is usually variable and often much higher than a loan rate.
The structural difference matters more than the headline rate. A loan forces discipline: fixed payments, a defined payoff date, and no temptation to add new charges. A credit card offers flexibility but punishes you if you carry a balance. For a repair in the $5,000 to $15,000 range, that distinction can mean hundreds or thousands of dollars in interest over the life of the debt.
Before you borrow, it helps to understand how contractors price the work itself. In our guide on choosing a reliable home improvement contractor, we explain how to compare bids and avoid inflated estimates, which directly affects how much you need to finance. A accurate quote is the foundation of any borrowing decision.
Interest and Term Comparison for a $5,000 to $15,000 Repair
To make the comparison concrete, consider a $10,000 repair financed over three years. A typical unsecured home improvement loan might carry an annual percentage rate (APR) between 7% and 12% for borrowers with good credit. A standard credit card might charge 18% to 25% APR, and a store-branded or contractor-offered card could start at 0% but jump to 26% or more after a promotional period.
Here is how the math plays out for a $10,000 balance repaid over 36 months:
- Home improvement loan at 9% APR: monthly payment around $318, total interest roughly $1,450.
- Credit card at 22% APR: monthly payment around $381 (if you pay it off in 36 months), total interest roughly $3,700.
- 0% promotional card for 12 months, then 26% APR: if you do not clear the balance within the promo period, the remaining $7,000 or so re-amortizes at a much higher rate, and total interest can exceed $4,500.
The gap is stark. On a $10,000 repair, choosing a loan over a standard credit card can save you more than $2,000 in interest. For a $15,000 repair, the savings scale proportionally. The lower the loan rate and the shorter the term, the wider the advantage. However, if you can repay a credit card balance in full within a 0% promotional window, the card can be cheaper than a loan. The key is honesty about your repayment capacity.
Term length also affects affordability. A five-year loan lowers your monthly payment but increases total interest. A three-year loan costs less overall but requires higher monthly cash flow. Credit cards offer minimum payments that feel manageable but can stretch repayment over a decade if you only pay the minimum. Always compare the total cost of credit, not just the monthly payment.
The Promotional Rate Trap on Contractor-Offered Credit Cards
Many contractors partner with financing companies to offer point-of-sale credit cards with enticing promises: "0% for 12 months" or "no payments until next year." These offers can be useful, but they come with traps that catch homeowners off guard.
First, deferred interest is not the same as zero interest. With a true 0% offer, you pay no interest during the promotional period. With deferred interest, interest accrues from day one and is waived only if you pay the full balance before the promo ends. If you leave even $100 unpaid, you can be charged retroactive interest on the entire original purchase. That $10,000 repair could suddenly carry a year's worth of interest at 26% APR, adding $2,600 to your balance overnight.
Second, promotional rates often come with fees. Some cards charge an annual fee, an origination fee, or a higher rate on new purchases. Third, the promotional period may be shorter than you expect, sometimes six months rather than twelve. Fourth, if you miss a payment, the promotional rate can be revoked immediately, and the penalty APR can exceed 29%.
Contractor-offered cards can be legitimate tools, but only if you read the fine print and have a clear plan to repay within the promotional window. If there is any chance you will carry a balance beyond the promo, a fixed-rate home improvement loan is almost always the safer and cheaper choice.
How to Compare the Total Cost of Each Option
Comparing a loan and a credit card is not about which has the lower monthly payment. It is about which costs less over the life of the debt and which fits your cash flow without risking late fees or penalty rates. Use a simple framework to evaluate both offers side by side.
Start by gathering the key numbers for each option:
- APR: the true annual cost of borrowing, including fees.
- Term or repayment period: how many months you will be in debt.
- Monthly payment: the fixed amount (for a loan) or the minimum plus your planned extra payment (for a card).
- Total interest: the sum of all interest charges over the repayment period.
- Fees: origination fees, annual fees, balance transfer fees, or prepayment penalties.
Once you have these numbers, calculate the total cost of credit for each option: total interest plus fees. The option with the lower total cost is generally the better deal, provided the monthly payment fits your budget. If one option has a lower total cost but a monthly payment you cannot comfortably afford, it is not the right choice. Cash flow matters as much as cost.
Also consider the tax treatment. Interest on a home equity loan or home equity line of credit (HELOC) may be tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Personal loans and credit card interest are generally not deductible. Consult a tax advisor for your specific situation, but do not let a potential deduction drive a borrowing decision that otherwise does not make sense.
Finally, think about the long-term relationship. A credit card balance can linger for years, especially if you continue to use the card for other purchases. A loan has a fixed endpoint. If you value predictability and want to avoid the risk of revolving debt, a loan is often the more disciplined choice.
When to Delay a Repair Versus Finance It
Not every repair needs to be financed immediately. Some problems are cosmetic and can wait; others are structural or safety-related and should be addressed promptly. The decision to delay versus finance depends on the urgency of the repair, the cost of waiting, and your current financial capacity.
Consider delaying a repair if the issue is purely aesthetic, if the repair cost is small enough to save for in a few months, or if financing would require a high-interest loan that strains your budget. For example, a dated vanity or a scratched floor can wait. But a leaking roof, a failing water heater, or an electrical hazard cannot. Delaying a necessary repair often leads to more extensive damage and higher costs later. A $500 roof patch today can become a $5,000 deck replacement after a season of water intrusion.
Finance the repair if it is urgent, if the cost of waiting exceeds the cost of borrowing, or if you have a stable income and can comfortably manage the monthly payment. Before you commit, request multiple quotes from licensed contractors to ensure you are financing a fair price. Platforms like Contractor.Homes connect homeowners with pre-vetted local pros and free quote requests, which can help you compare bids and avoid overpaying. A lower project cost reduces the amount you need to borrow and the interest you pay.
If you decide to finance, choose the option with the lowest total cost that fits your cash flow. A home improvement loan with a fixed rate and a term of three to five years is often the most predictable route for mid-sized repairs. A credit card can work if you have a 0% promotional offer and a guaranteed plan to repay before it expires, but the risk of deferred interest and penalty rates makes it a gamble. For most homeowners, the loan is the safer bet.
Practical Steps to Choose the Right Financing
Before you sign any loan or card agreement, take these steps to protect yourself and your budget.
- Get at least three contractor quotes. The project cost drives the financing amount, so competitive bids are essential.
- Check your credit score. A higher score unlocks lower loan rates and better credit card offers.
- Shop for loan rates from multiple lenders. Credit unions, online lenders, and banks may offer different terms.
- Read the fine print on promotional offers. Look for deferred interest, penalty APRs, and fees.
- Calculate the total cost of credit for each option. Do not compare monthly payments alone.
- Have a repayment plan. If you use a credit card, set a fixed payoff date and automate payments.
These steps take an hour or two but can save you thousands. The goal is not to find the lowest monthly payment but the lowest total cost that you can comfortably repay. A repair is an investment in your home; the financing should not become a burden that undermines that investment.
In the end, the choice between a home improvement loan and a credit card for small repairs comes down to discipline and math. Loans offer structure, lower rates, and a clear payoff date. Credit cards offer flexibility but carry higher rates and the risk of revolving debt. For most mid-sized repairs, a fixed-rate loan is the more cost-effective and predictable option. If you use a credit card, do so only with a 0% promotional offer and a firm plan to repay before it expires. Either way, start with accurate contractor quotes so you finance the right amount at the best possible terms.
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.