Renovation Deposit Protection: What Homeowners Should Know
Renovation deposit protection what homeowners should know before paying upfront. Call (833)-211-1668 to compare vetted local contractors and avoid surprise bills.
By Ethan Turner
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
A renovation deposit is often the first real money a homeowner hands over, and it is also the moment when project risk shifts from the contractor to you. Pay too much upfront and you lose leverage. Pay too little and a legitimate contractor may walk away or struggle to buy materials. Understanding how deposit protection works, what legal limits apply in your state, and how to structure payments around milestones can mean the difference between a smooth remodel and a drawn-out financial fight. This guide explains the rules, the red flags, and the practical steps that keep your money and your project on solid ground.
What a Renovation Deposit Actually Is
A renovation deposit is an upfront payment a homeowner makes before work begins. Contractors use it to reserve your spot on their schedule, purchase materials, pull permits, and cover mobilization costs. On a kitchen remodel, for example, a deposit might cover the cost of cabinetry ordered weeks in advance. On a roofing project, it often pays for shingles and underlayment that must be delivered before the crew arrives.
The confusion arises because the word deposit gets used loosely. A true deposit is typically a small percentage of the contract price, sometimes 10 percent to 30 percent, and it is applied to the total job cost. A down payment may be larger and tied to a specific phase. A retainer is usually a fee for design or consultation work. Knowing which one you are paying matters because the legal protections attached to each can differ.
Deposit protection, in practical terms, is the combination of contract language, state law, payment method, and documentation that ensures your money is either used for your project or returned to you if the contractor fails to perform. Without those layers, a deposit is simply an unsecured loan to a business you may not know well.
Why Deposit Protection Matters More Than Ever
Home improvement fraud complaints spike whenever construction demand outpaces contractor supply. After major storms, during housing booms, or in fast-growing metro areas, unlicensed operators appear, collect deposits, and disappear. Even well-intentioned contractors can run into cash flow problems, using one client's deposit to finish another client's job. That pattern, sometimes called robbing Peter to pay Paul, is one of the most common reasons remodels stall.
Homeowners also face subtler risks. A contractor may quote a low price, collect a large deposit, then claim the scope changed and demand more money before continuing. Or a contractor may go out of business mid-project, leaving you with a half-finished bathroom and a deposit that is gone. In each case, the strength of your deposit protection determines whether you recover money or absorb the loss.
There is also the matter of leverage. Once a large deposit is paid, your ability to insist on quality, timelines, and corrections weakens. Contractors who already have most of your money have less incentive to prioritize your punch list. Structuring deposits and progress payments so that compensation follows performance is one of the simplest ways to protect yourself.
State Laws That Limit Deposits
There is no single federal rule governing renovation deposits. Instead, each state sets its own limits, and some states delegate authority to local licensing boards. California, for example, generally caps upfront deposits for home improvement contracts at 10 percent of the contract price or $1,000, whichever is less, with some exceptions for special-order materials. New York has specific rules for home improvement contracts, including limits on deposits and requirements for written agreements. Other states, such as Florida and Texas, regulate deposits through licensing statutes and consumer protection laws rather than a flat percentage cap.
Because the rules vary so widely, the first step in protecting yourself is to verify what your state requires. Your state contractor licensing board, attorney general's office, or consumer protection agency typically publishes plain-language guidance. If a contractor asks for a deposit that exceeds your state's limit, that is not a minor detail. It is a warning sign that the contractor either does not know the law or chooses to ignore it.
Some states also require contractors to place deposits in a trust account or to provide specific disclosures about how the money will be used. These requirements exist precisely because deposits are vulnerable. When a contractor commingles deposit funds with general operating money, those funds can vanish if the business hits trouble. Trust account requirements create a paper trail and, in some cases, a legal claim if the money is misused.
Contract Terms That Protect Your Deposit
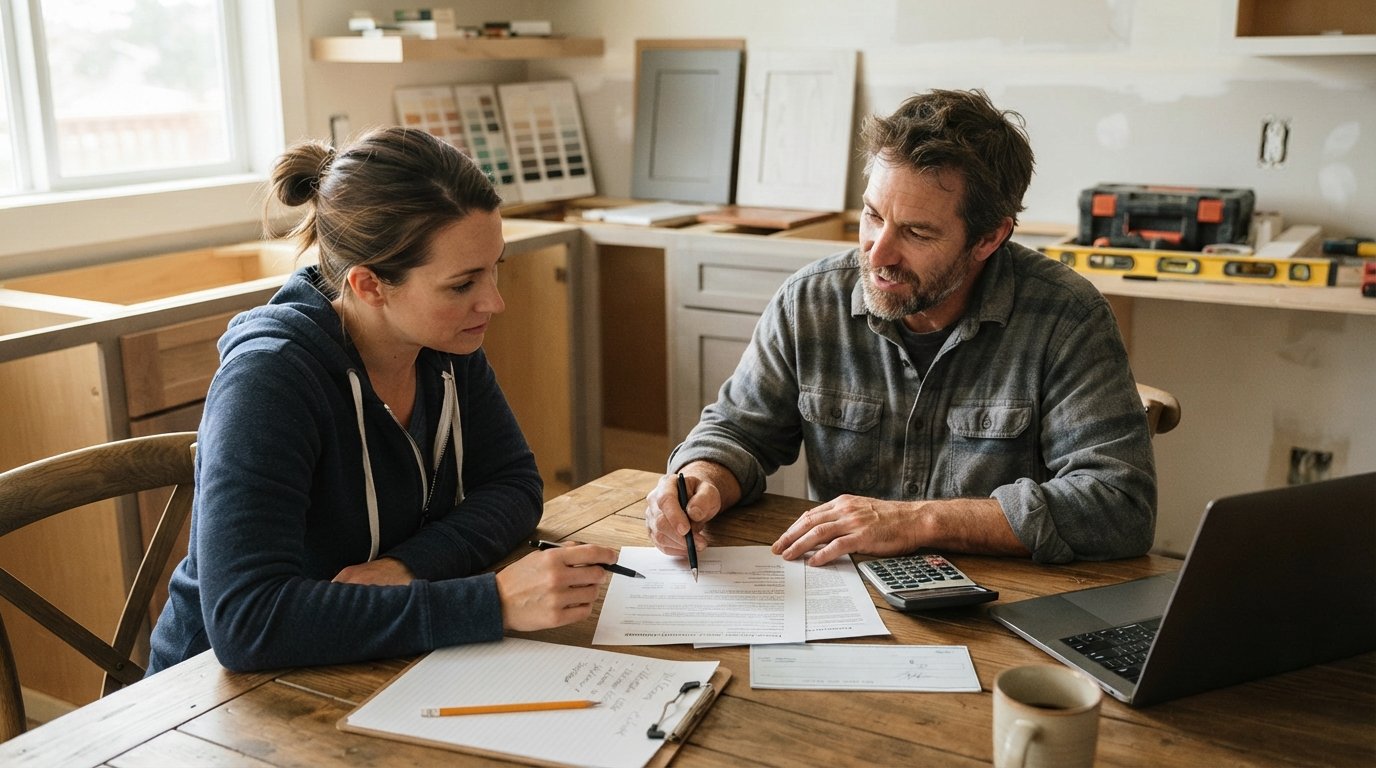
The contract is your primary tool for deposit protection. A well-written agreement does more than state a price. It defines when money changes hands, what triggers each payment, and what happens if the project stops. Before signing, read the payment section carefully and insist on language that ties deposits to specific, verifiable events.
Here are the contract elements that matter most for protecting a renovation deposit:
- Deposit amount and legal limit: State the exact dollar amount and confirm it complies with your state's cap.
- Use of funds: Specify that the deposit will be used only for your project, including materials, permits, and mobilization.
- Milestone schedule: List each phase (demo, rough-in, drywall, finishes) and the payment tied to its completion.
- Refund conditions: Explain when and how the deposit is refundable if the contractor cancels or fails to start.
- Lien waivers: Require the contractor to provide lien waivers from suppliers and subcontractors as payments are made.
Lien waivers deserve special attention. If a contractor fails to pay a supplier, that supplier can file a mechanics lien against your home, even if you already paid the contractor in full. A deposit that is supposed to cover materials but never reaches the supplier can leave you paying twice: once to the contractor and once to the supplier to clear the lien. Requiring conditional lien waivers at each payment stage closes that gap.
It also helps to include a start date and a completion date, along with a clause that addresses delays. If the contractor does not start within a reasonable window, you should have the right to cancel and recover your deposit. Without that clause, you may be stuck waiting while your deposit sits in someone else's account.
How to Pay: Methods That Preserve Recovery Options
The payment method you choose has a direct impact on your ability to recover a deposit. Cash is the worst option because it leaves no trace and offers no dispute mechanism. Personal checks are better but still slow to reverse. Credit cards offer strong consumer protections, including the ability to dispute charges for services not rendered. Debit cards offer weaker protections but still create a record.
For larger deposits, some homeowners use escrow services or title companies to hold funds until specific milestones are met. Escrow adds a layer of neutrality: the contractor knows the money exists, and you know it will not be released without proof of progress. The cost of escrow is usually a small percentage of the project, and it can be worth every dollar on a six-figure remodel.
If you pay by check, write the check to the licensed business name, not to an individual. Never pay a deposit to a personal account when the contract is with a company. If the contractor asks you to make the check out to a different name, ask why in writing. That request is sometimes legitimate, but it is also a common tactic in fraud cases.
Red Flags That Signal Deposit Risk
Certain behaviors should stop you from handing over a deposit, no matter how attractive the price. A contractor who demands a large cash deposit before providing a written contract is a clear risk. So is a contractor who refuses to provide a license number, insurance certificate, or a physical business address. These are not minor administrative gaps. They are indicators that the person may not be accountable if something goes wrong.
Other warning signs include:
- Pressure to sign immediately or to pay a deposit today to lock in a discount.
- A price that is dramatically lower than other bids, with no clear explanation.
- Requests to pay a deposit to a person rather than a licensed business entity.
- No written timeline, no scope of work, and no payment schedule.
- Reluctance to provide references or to let you visit a current job site.
Any one of these flags may have a reasonable explanation, but together they paint a picture of a contractor who is either disorganized or dishonest. Either way, your deposit is at risk. When you are comparing bids, pay attention to how each contractor handles the deposit conversation. A professional will explain the deposit, tie it to specific costs, and put everything in writing. If you want help comparing estimates side by side, our guide on why construction estimates change explains how to spot the difference between legitimate adjustments and bait-and-switch pricing.
Steps to Take Before You Pay a Deposit
Protecting your deposit starts before the first payment. The most effective approach is to treat the deposit as part of a broader verification process. You are not just hiring a contractor; you are entering a financial relationship that should be documented, insured, and legally compliant.
Follow these steps in order:
- Verify the contractor's license, insurance, and business registration with your state and local authorities.
- Get at least three written estimates and compare the scope, timeline, and payment terms, not just the total price.
- Read the contract carefully, paying special attention to deposit limits, refund conditions, and lien waiver requirements.
- Confirm that the deposit amount complies with your state's home improvement laws.
- Choose a payment method that preserves your ability to dispute or recover funds.
Once those steps are complete, document everything. Keep copies of the contract, the deposit check or receipt, the contractor's license number, and any text messages or emails about the project. If a dispute arises later, that paper trail is often the difference between a quick resolution and a long legal battle.
It also helps to photograph the job site before work begins. Date-stamped photos establish the condition of your home at the start and can be useful if a contractor claims pre-existing damage or disputes the scope of work. For larger projects, consider a simple project journal that records each payment, each milestone, and each conversation. This is not about distrust. It is about creating a record that protects both parties.
What to Do If a Contractor Takes Your Deposit and Disappears
If a contractor collects a deposit and stops responding, act quickly. The first step is to send a written demand letter by certified mail, return receipt requested. The letter should state the amount paid, the work not performed, and a deadline for response. Keep a copy for your records. In many cases, a formal demand letter prompts a response because it signals that you are prepared to escalate.
If the contractor does not respond, you have several options. You can file a complaint with your state contractor licensing board, which may investigate and take disciplinary action. You can file a claim in small claims court if the amount is within your state's limit, or in civil court for larger amounts. You can also contact your state attorney general's consumer protection division, which often tracks patterns of complaints against the same contractor.
If you paid by credit card, dispute the charge promptly. Credit card issuers generally allow disputes for services not rendered, and the burden falls on the merchant to prove delivery. If you paid by check, your bank may be able to help if the check was recently cashed, but the window is short. This is one more reason to avoid cash and to keep payments traceable.
Finally, consider whether a mechanics lien is a risk. If the contractor failed to pay suppliers, those suppliers may file liens against your property. You can often resolve this by paying the supplier directly and then pursuing the contractor for reimbursement, but the process is easier to prevent than to fix. That is why lien waivers at each payment stage are so valuable.
Working With Vetted Contractors to Reduce Deposit Risk
The most reliable deposit protection is prevention. Working with pre-vetted, licensed contractors dramatically reduces the chance that your deposit will be misused. Vetted contractors have a verifiable track record, carry insurance, and understand the legal requirements in their state. They are also more likely to use clear contracts, milestone payments, and lien waivers because those practices protect them too.
Platforms like Contractor.Homes connect homeowners with local professionals who have been screened for licensing and insurance, which means you start the deposit conversation from a stronger position. When you request quotes through a marketplace, you can compare multiple contractors side by side and see how each one handles deposits, payment schedules, and contract terms. That comparison is one of the best defenses against overpaying upfront or hiring someone who cannot deliver.
It also helps to ask each contractor directly: How much deposit do you require, and why? A contractor who can explain the deposit in terms of specific costs, such as materials, permits, and scheduling, is usually operating transparently. A contractor who is vague or defensive about the deposit is showing you how they will behave when a problem arises.
Deposit Protection Checklist for Homeowners
Before you write a deposit check, run through a simple checklist. This is not legal advice, but it is a practical framework that covers the most common risks. If you can answer yes to each item, your deposit is far better protected than the average homeowner's.
- I have verified the contractor's license, insurance, and business registration.
- I have a written contract that states the deposit amount and how it will be used.
- The deposit complies with my state's home improvement laws.
- Payments are tied to milestones, not to dates alone.
- I have a plan for lien waivers and final payment.
- I am paying by a method that allows disputes or recovery.
- I have documented the pre-project condition of my home.
Keep this checklist with your project file and revisit it before each payment. Deposit protection is not a one-time decision. It is an ongoing practice that continues through the final walkthrough and the release of the last payment. The more disciplined you are at each stage, the less likely you are to end up in a dispute.
Renovation deposit protection comes down to three things: knowing the law, structuring payments around performance, and working with contractors who are accountable. Do those three things, and your deposit becomes what it was always meant to be: a reasonable commitment that moves your project forward rather than a gamble on someone else's reliability.